



The stablecoin market carried a total capitalization of $305.149 billion, with USDT dominance at 60.09% in early September 2026, and nearly all of that float now sits behind a published reserve disclosure of some kind. Circle refreshes USDC reserve holdings weekly, Tether republishes token circulation daily and reserve totals with each reserves report, and Paxos issues two separate documents each month for PYUSD.
Statute now sets the floor those cadences have to clear. The GENIUS Act framework bars issuing a payment stablecoin in the United States without a federal or state license beginning on January 18, 2027, and under MiCA, Article 30 already requires issuers of asset-referenced tokens to update circulation and reserve composition at least monthly. The figures below cover reserve composition, attestation cadence, chain-level concentration, and the rules hardening around all of it.
Key Takeaways
- As of September 3, 2026, Circle reported USDC in circulation of $74.3 billion against total reserves of $74.5 billion, so reserves sat above circulating supply.
- As of September 7, 2026, Tether token net circulation reached $183,354,746,628.48, the largest reserve pool any single issuer has to account for.
- Section 4 requires reserves backing outstanding payment stablecoins on at least a 1-to-1 basis, and limits permitted Treasury holdings to a remaining maturity of 93 days or less.
- The Circle Reserve Fund ran a weighted average maturity of 10 days with daily liquid assets at 100.0%, far inside that statutory ceiling.
- Paxos publishes two distinct documents each month, one self-reported portfolio composition released 5 business days after month-end and one independent attestation.
- EURC, Circle’s euro token, showed €398.0 million in circulation against €400.8 million of reserves on the same weekly cadence.
Editor’s Choice
- Total stablecoin market capitalization: $305.149 billion.
- Tether issuer total assets: $187,751,825,408.00 at the 30 June 2026 reserves report.
- Tether issuer total liabilities in the same report: $183,642,296,213.00.
- Tether issuer net equity in the same report: $4,109,529,195.00.
- USDC issued over the trailing 365 days: $332.3 billion.
- USDC redeemed over the trailing 365 days: $330.5 billion.
Stablecoin Supply Backed by Published Reserves
- DefiLlama tracked Tether (USDT) at $183.363 billion and USD Coin (USDC) at $74.375 billion across all monitored chains.
- Circle reported total USDC reserves of $74.5 billion against $74.3 billion in circulation, and states that USDC is always redeemable 1:1 for US dollars.
- The Tether Issuer reported total assets of $187,751,825,408.00 against liabilities of $183,642,296,213.00, and states that Tether tokens are backed 100% by Tether’s Reserves.
- DefiLlama recorded a 7-day change of $1.616 billion, or 0.53%, in total stablecoin market cap.
- The two issuers answer different questions. Circle publishes a reserve total; Tether publishes an issuer balance sheet. Readers tracking stablecoin market capitalisation see only the supply half of that pair.
| Issuer | Token | In circulation | Reserves or total assets | Reserve data as of |
|---|---|---|---|---|
| Circle | USDC | $74.3 billion | $74.5 billion | September 3, 2026 |
| Tether | USDT | $183,354,746,628.48 | $187,751,825,408.00 | June 30, 2026 |
| Circle | EURC | €398.0 million | €400.8 million | September 3, 2026 |
Source: Circle Transparency 2026, Tether Transparency 2026
About This Data
Every figure here comes from nine Tier 1 primary sources: issuer transparency pages, a fund manager’s portfolio disclosure, the enrolled statutory text, a Treasury press release, a Federal Register record, and the consolidated EU regulation. The compilation window runs from 2023 to September 2026. Only primary or official publishers qualify. Figures are reviewed on a rolling basis and updated when the underlying sources publish new editions.

Do stablecoins have reserves?
Fiat-backed stablecoins do, and the largest issuers publish the totals. Circle reported total USDC reserves of $74.5 billion against $74.3 billion in circulation, while the Tether Issuer reported total assets of $187,751,825,408.00 against liabilities of $183,642,296,213.00 in its 30 June 2026 report. Composition and cadence differ by issuer.
What are the top 3 stablecoins?
DefiLlama’s stablecoin table lists Tether (USDT) at $183.363 billion, USD Coin (USDC) at $74.375 billion, and Sky Dollar (USDS) at the top of its rankings. The first two account for the bulk of the tracked float, which is why their disclosure practices set the sector’s reference standard.
USDC Reserve Composition and Disclosure Cadence
- Circle discloses USDC reserve holdings on a weekly basis along with the associated mint and burn flows, the fastest published cadence among the largest issuers.
- A Big Four accounting firm provides monthly third-party assurance that the value of USDC reserves is greater than the amount of USDC in circulation.
- Those reports follow attestation standards set out by the American Institute of Certified Public Accountants.
- The published reserve buckets are other bank deposits, deposits at Systemically Important Institutions, overnight reverse Treasury repo, and Treasuries under 3 months.
- Over the trailing 30 days, USDC issuance of $37.5 billion against redemptions of $35.3 billion produced a $2.3 billion change in circulation.
Gross flow dwarfs net change at every horizon, which is the practical case for weekly rather than monthly reporting. A monthly snapshot of USDC reserves would hide tens of billions of gross issuance behind a low-single-digit-billion net figure.
Recent Developments
- August 17, 2026: Treasury issued a Notice of Proposed Rulemaking on its implementation of section 3 of the GENIUS Act, with the announcement and comment details on its own site.
- August 18, 2026: Comments on the proposal must be received on or before October 19, 2026, per the Federal Register proposed rule.
- June 30, 2026: Tether’s most recent reserves report covers the Tether Issuer’s assets and liabilities as of 30 June 2026.
- July 2026: Paxos listed monthly PYUSD attestation reports for 2026, running from Jan through Jul.
- September 2026: The Circle Reserve Fund posted a 7-day yield of 3.61% and a 1-day yield of 3.62%.
USDT Reserve Attestation Figures
- The Tether Issuer reported total assets of $187,751,825,408.00 in the 30 June 2026 reserves report.
- Total liabilities stood at $183,642,296,213.00 on the same date.
- Net equity stood at $4,109,529,195.00, the buffer between the two.
- The Tether Issuer is Tether International, S.A. de C.V., the entity named in the reserves report.
- Tether typically refreshes its circulation metrics daily, while the reserve figures date to the last Reserves Report, so two numbers on the same page carry different vintages.
By the numbers: The 30 June 2026 reserves report shows assets of $187,751,825,408.00 against liabilities of $183,642,296,213.00, leaving net equity of $4,109,529,195.00. The cushion equals about 2.2% of the liabilities it stands behind. Circulation on the same page refreshes daily, so the equity line is the slowest-moving number Tether publishes.
Across CoinLaw’s stablecoin and regulatory coverage, the recurring pattern is that disclosure frequency improves faster than disclosure depth. A periodic balance sheet published beside a daily supply counter tells readers a great deal about supply and comparatively little about what backs it on any given day.
USDT Reserve Concentration by Blockchain
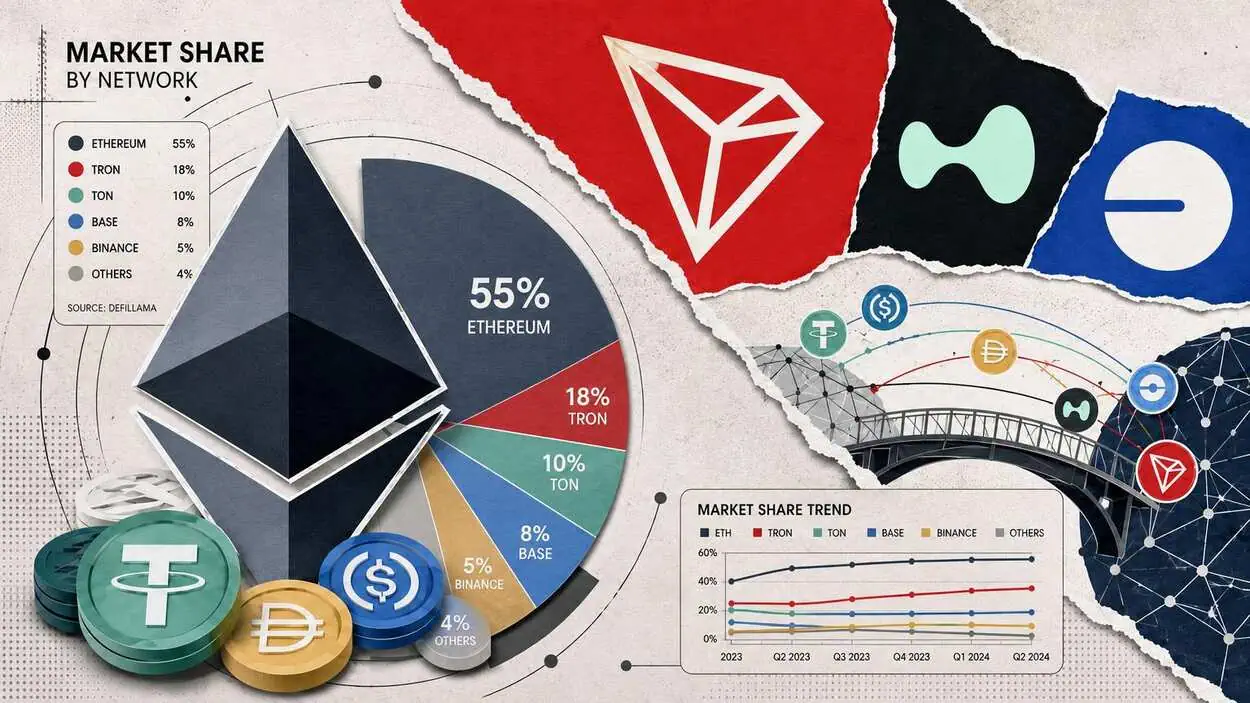
- Tron carried Tether token net circulation of $92,294,275,421.48, the largest single-chain concentration.
- Ethereum carried $86,276,532,724.57 on the same date.
- Solana carried $2,761,408,257.77, Aptos $631,679,940.80, Ton $605,788,044.43 and Avalanche $324,285,878.12.
- Total authorized supply on Tron reached $94,268,087,063.64, of which $1,973,811,642.17 was authorized but not issued, a distinction that separates minted supply from live float.
- Tether is no longer issuing or obligated to redeem tokens on the Kusama, Bitcoin Cash SLP, Omni Layer, EOS, and Algorand blockchains.
Reserve attestation is a token-level exercise, so it never speaks to where the tokens live. Two chains carrying the overwhelming majority of the float is an operational fact no reserve report is designed to surface, and a reader comparing Tether against its own disclosures has to assemble it manually.
GENIUS Act Reserve Assets and the 93-Day Maturity Cap
- Section 4 requires a permitted payment stablecoin issuer to maintain identifiable reserves backing outstanding payment stablecoins on at least a 1-to-1 basis.
- Treasury bills, notes or bonds qualify only with a remaining maturity of 93 days or less, or when issued with a maturity of 93 days or less.
- Repurchase agreements qualify when they carry an overnight maturity and are backed by Treasury bills maturing in 93 days or less.
- Shares in a registered government money market fund qualify only where the fund invests solely in the underlying assets the statute already lists.
- Reverse repurchase agreements also qualify when they carry an overnight maturity.
| Permitted reserve asset | Condition set by Section 4 of the GENIUS Act |
|---|---|
| US coins and currency, or Federal Reserve account balances | Listed without a maturity condition |
| Demand deposits or insured shares at an insured depository institution | Withdrawable upon request at any time |
| Treasury bills, notes or bonds | Remaining maturity of 93 days or less |
| Overnight repurchase agreements | Backed by Treasury bills maturing in 93 days or less |
| Overnight reverse repurchase agreements | Collateralized by Treasury notes, bills or bonds |
| Registered government money market fund shares | Invested solely in the assets listed above |
Source: GENIUS Act, Public Law 119-27, Section 4, 2025
Why it matters: The statute converts reserve composition from a disclosure choice into a permitted-asset list. A 93-day Treasury maturity ceiling and an overnight condition on repurchase agreements mean an issuer cannot reach further out the curve for yield and then disclose its way to compliance, which changes what a monthly reserve report is actually testing.
Treasury’s GENIUS Act Rulemaking Timeline
- Treasury issued the Notice of Proposed Rulemaking on August 17, 2026, seeking public comment on its implementation of section 3.
- Treasury Secretary Scott Bessent said Treasury is moving quickly to implement that framework.
- Beginning on January 18, 2027, the expected effective date, a person generally may not issue a payment stablecoin in the United States without an appropriate federal or state license.
- Beginning on July 18, 2028, digital asset service providers generally may not offer or sell payment stablecoins to persons in the United States unless a licensed issuer issued them.
- In the Federal Register, the proposed rule runs 24 pages, at 53368-53391, under RIN 1505-AC95.
Attestation Versus Audit and What Issuers Actually Publish
- Section 4 requires an issuer to have the previous month-end report examined each month by a registered public accounting firm.
- The Chief Executive Officer and Chief Financial Officer must each month certify the accuracy of the monthly report.
- A knowingly false certification carries the same criminal penalties as those set forth under section 1350(c) of title 18, United States Code.
- Paxos self-reports its portfolio composition 5 business days after month-end, and those reports have not been subjected to independent review.
- KPMG LLP conducts its examination in accordance with attestation standards established by the American Institute of Certified Public Accountants.
| Document | Who prepares it | What it covers | Independent review |
|---|---|---|---|
| Paxos monthly self-report | Paxos | Portfolio composition, 5 business days after month end | No |
| PYUSD monthly attestation | KPMG LLP | Reserve examination under AICPA standards | Yes |
| USDC monthly assurance | A Big Four accounting firm | Reserves greater than USDC in circulation | Yes |
| Statutory monthly examination | Registered public accounting firm | The previous month-end report | Yes |
Source: Paxos PYUSD Transparency 2026, Circle Transparency 2026, GENIUS Act Section 4, 2025
Has USDC been audited?
Circle publishes monthly third-party assurance in which a Big Four accounting firm confirms that the value of USDC reserves is greater than the amount of USDC in circulation, under AICPA attestation standards. An examination of that kind tests one assertion at one date, a narrower exercise than an annual audit opinion.
The Circle Reserve Fund as a Second Disclosure Layer
- Circle states that Treasuries and overnight reverse repurchase agreements held as USDC reserves may sit in custodial accounts, in a separately managed account, or within the Circle Reserve Fund, a 2a-7 money market fund managed by BlackRock.
- The fund reported a weighted average maturity of 10 days and a weighted average life of 10 days.
- Weekly liquid assets and daily liquid assets both stood at 100.0% on the same date.
- The 30-day SEC yield was 3.61% and the unsubsidized 7-day yield 3.51%.
- Net shareholder flows registered $0 on the reported date.
Key finding: The Circle Reserve Fund’s weighted average maturity of 10 days sits far inside the 93-day Treasury ceiling Section 4 permits, and its daily liquid assets stood at 100.0%. Issuers are choosing liquidity well beyond what the statute demands, so the binding constraint on reserve duration today is redemption risk rather than the law.
EURC Reserves and Euro Stablecoin Disclosure
- EURC reported €398.0 million in circulation against total reserves of €400.8 million.
- Over the trailing 365 days, EURC issuance reached €3080.5 million against redemptions of €2887.1 million, a €193.4 million change in circulation.
- Over the trailing 7 days, EURC issued €94.9 million and redeemed €92.7 million.
Euro-denominated supply sits orders of magnitude below the dollar book, yet it carries the same weekly disclosure treatment. Issuers operating inside the EU (MiCA) perimeter have a statutory reason for that consistency.
MiCA Disclosure Duties for EU Issuers
- Article 30 requires issuers of asset-referenced tokens to disclose the amount in circulation and the value and composition of the reserve of assets, updated at least monthly.
- Issuers must publish a brief, clear, accurate, and transparent summary of the audit report as well as the full and unredacted audit report.
- Issuers must also disclose any event that has or is likely to have a significant effect on token value or on the reserve of assets, as soon as possible.
- Section 4 sets its own monthly floor, requiring publication of the total number of outstanding payment stablecoins and the amount and composition of reserves, including the average tenor and geographic location of custody.
| Obligation | Where it appears |
|---|---|
| Monthly update of circulation and reserve value and composition | MiCA Article 30 |
| Publication of the full and unredacted reserve audit report | MiCA Article 30 |
| Prompt disclosure of events affecting the reserve | MiCA Article 30 |
| Monthly publication of outstanding supply and reserve composition | GENIUS Act Section 4 |
| Monthly examination and CEO and CFO certification | GENIUS Act Section 4 |
Source: EUR-Lex and US Congress, 2026
Both regimes land on a monthly floor, yet they ask for different artifacts. MiCA reaches for the audit report itself; the US statute reaches for an examined report plus a signed certification, which is where regulatory compliance cost concentrates for a dual-listed issuer.
PYUSD Disclosure Under the Paxos Two-Document Model
- Paxos Trust Company N.A. issues PayPal USD, PayPal’s stablecoin designed for payments.
- Attestation reports posted on or after February 28, 2025 are issued by KPMG LLP, an independent third-party accounting firm.
- Reports posted before February 28, 2025 were issued by WithumSmith+Brown, PC.
- Paxos describes itself as the first regulated blockchain infrastructure platform, with a policy commitment to keeping attestation reports publicly available.
| Attestation period | Attesting firm |
|---|---|
| On or after February 28, 2025 | KPMG LLP |
| Before February 28, 2025 | WithumSmith+Brown, PC |
Source: Paxos PYUSD Transparency, 2026
The two-document model is the clearest illustration of the attestation gap anywhere in the sector. Readers of PYUSD disclosures get a fast, unreviewed number and a slower, reviewed one, and only the second carries an accounting firm’s name.
Reserve Transparency Gaps That Remain
- Chain concentration sits outside attestation scope: Tron and Ethereum carry $92,294,275,421.48 and $86,276,532,724.57 of Tether token net circulation.
- Reserve totals move far faster than reports, with $332.3 billion issued and $330.5 billion redeemed in USDC over 365 days against a monthly assurance cadence.
- Comparability stays limited, since Circle publishes reserve buckets down to deposit type and Treasury tenor while Tether publishes an issuer-level summary of assets, liabilities, and net equity.
- Vintage mixing persists on issuer pages, because circulation metrics refresh daily while the assets and liabilities line dates to the last Reserves Report.
Reserve transparency is only one axis of stablecoin oversight, and anti-money-laundering (AML) controls run on a separate track with their own reporting obligations. The reserve question also has a settled history, because algorithmic stablecoins carried no comparable disclosure surface at all, which is a large part of why the fiat-backed model became the regulatory template.
Conclusion
The reserve numbers behind a $305.149 billion stablecoin market are now published on cadences running from daily to periodic, with USDC total reserves of $74.5 billion refreshed weekly at one end and an issuer balance sheet at the other. What has changed is that the cadence is becoming a legal minimum rather than a competitive choice: a monthly reserve publication, a monthly examination by a registered public accounting firm, and a monthly CEO and CFO certification all sit in Section 4, and the licensing gate opens on January 18, 2027.
The most useful signal for readers is the distance between what issuers publish today and what the statute will demand. Comparing USDC and USDT side by side still asks a reader to reconcile two reporting philosophies. On duration, they already sit well inside the line; on cadence, they are close to it, and on comparability, they remain far apart. Treasury professionals and policy researchers tracking that gap get more from the composition tables than from the headline reserve total.