
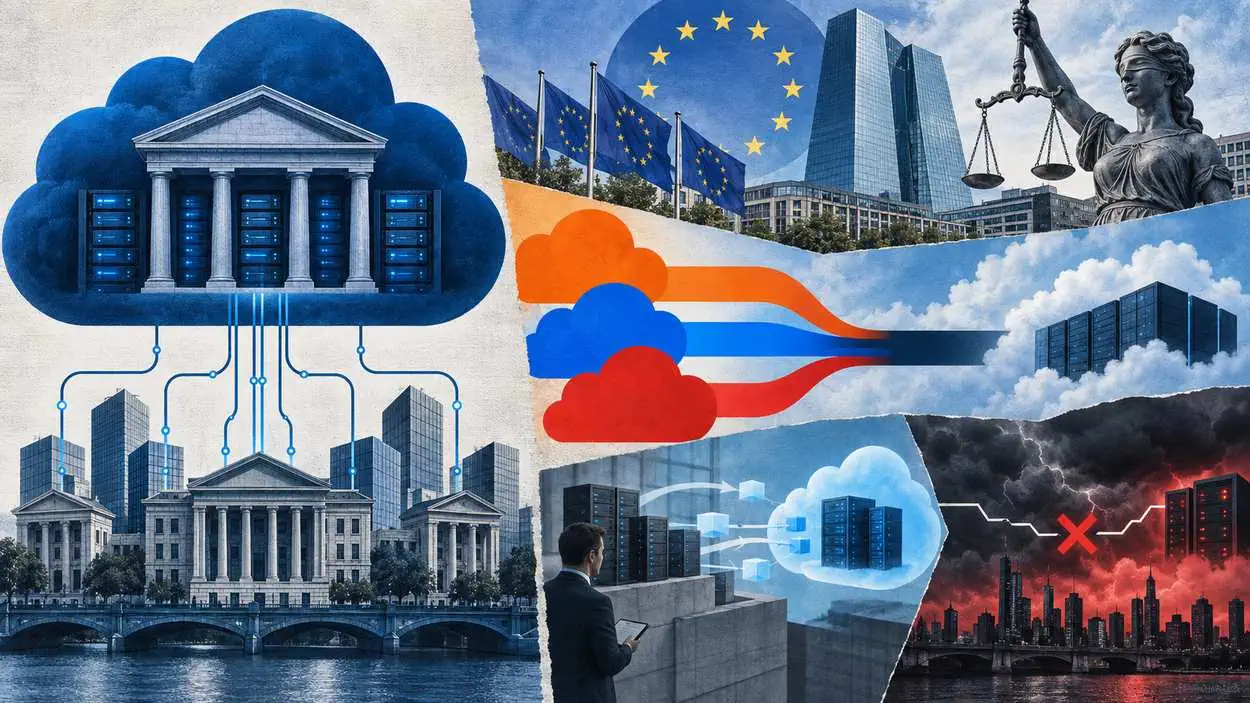




Cloud services account for approximately 15% of all outsourcing contracts at the eurozone’s largest banks. Yet essentially all significant institutions supervised by the European Central Bank now use cloud services. The latest cloud computing in financial services statistics show that money is flowing to a short list of vendors. In the Bank of England and FCA’s 2024 survey, the top three third-party providers of cloud accounted for 73% of all named providers.
Regulators have moved from watching that concentration to supervising it. The European Supervisory Authorities designated 19 critical ICT third-party providers on 18 November 2025. In London, the Bank of England, the PRA and the FCA start overseeing the first Critical Third Parties on Monday 13 July 2026. The figures below track bank adoption, hyperscaler revenue, supplier concentration, exit risk and outage exposure through July 2026.
Key Takeaways
- At banks the ECB supervises, cloud services account for approximately 15% of all outsourcing contracts, with half of these contracts covering critical or important functions.
- UK firms reported that the top three third-party providers of cloud accounted for 73% of all named providers in the 2024 Bank of England and FCA survey.
- Among contracts covering critical functions, around 20% cannot be reintegrated by the banks in case of issues, and around 5% cannot be substituted.
- The European Supervisory Authorities’ list names 19 critical ICT third-party service providers under the Digital Operational Resilience Act.
- Google Cloud revenues increased 82% to $24.8 billion in the quarter ended June 30, 2026, the fastest rate of the three hyperscalers.
- A survey of banks found that North American banks had migrated just 12% of their total workloads to the cloud, with European banks at 5%.
Editor’s Choice
- AWS quarterly sales: $42.2 billion, up 37% year-over-year, in the second quarter.
- Microsoft Cloud revenue: $59.3 billion, up 27% year-over-year, for the quarter ended June 30.
- Azure annual revenue: Azure revenue surpassed $100 billion for the first time in Microsoft’s fiscal year.
- Public cloud spending forecast: Gartner forecast worldwide end-user spending on public cloud services to total $675.4 billion in 2024.
- Non-EU critical services: 73 significant institutions are using critical services provided from non-EU countries.
- Outsourcing budget concentration: more than 30% of the total outsourcing budget of significant banks is concentrated on ten providers.
Cloud Computing in Financial Services Statistics: Bank Adoption Rates
- Sources: 21 sourced figures, 18 from regulators, government bodies and company earnings releases, and 3 from industry and research surveys.
- Window: sources published between 2023 and July 2026.
- Selection: only primary or official data that could be checked against the source’s own wording qualified.
- Refresh: figures are reviewed on a rolling basis and updated when sources publish new editions.
- In its own stocktake, the European Central Bank found that essentially all significant institutions under its supervision use cloud services.
- Half of the cloud contracts cover the outsourcing of critical or important functions, and cloud expenses are among the fastest-rising outsourcing costs.
- Most of the cloud providers used by significant institutions are located outside the EU.
- Per an industry survey cited by the Program on International Financial Systems, as of 2021, more than 90% of responding banks had adopted cloud for at least some workloads.
- Another survey found a third of all IT spending at banks was allocated to public cloud, up from less than 20% in 2018.
- The European Banking Authority’s Risk Assessment Questionnaire shows that outsourcing risks have increased considerably in banks’ perceptions, with cloud dependency cited as one driver.
| Adoption indicator | Value | Period |
|---|---|---|
| ECB significant institutions using cloud services | Essentially all | 2024 |
| Cloud share of all outsourcing contracts | Approximately 15% | 2024 |
| Cloud contracts covering critical or important functions | Half | 2024 |
| Responding banks with cloud for some workloads | More than 90% | 2021 |
| Bank IT spending allocated to public cloud | A third | Early pandemic |
Source: European Central Bank Banking Supervision 2024, Program on International Financial Systems 2023
How many banks use cloud computing?
Essentially all significant institutions supervised by the European Central Bank use cloud services, according to the ECB’s own stocktake. Earlier survey data cited by the Program on International Financial Systems shows more than 90% of responding banks had adopted cloud for at least some workloads as of 2021. The gap is one of breadth versus depth: adoption is near-universal among large banks, while the share of work actually running in the cloud stays small.

Hyperscaler Cloud Revenue in 2026
- Amazon reported that AWS net sales increased 37%, its fastest growth in 18 quarters, to a $169 billion annualized revenue run rate.
- Microsoft said revenue in Intelligent Cloud was $39.3 billion and increased 32%.
- Microsoft’s commercial remaining performance obligation increased 84% to $678 billion, a measure of contracted future revenue.
- Alphabet said Google Cloud growth was led by Google Cloud Platform across enterprise AI Solutions and enterprise AI Infrastructure, as well as core GCP services.
Recent Developments
- July 2026: The UK Government designated four major global cloud services and technology providers as Critical Third Parties.
- July 13, 2026: The Bank of England, the PRA and the FCA began overseeing the first Critical Third Parties under the new regime.
- July 22, 2026: Alphabet revenues increased 24% to $119.8 billion, its 12th consecutive quarter of double-digit revenue growth.
- July 29, 2026: Microsoft revenue was $90.0 billion and increased 18% for its fiscal fourth quarter.
- July 30, 2026: Amazon net sales increased 20% to $200.6 billion in the second quarter.
Cloud Provider Concentration in UK Financial Services
- The Bank of England and FCA found that a third of all current AI use cases deployed by respondents are third-party implementations, up from 17% in 2022, a shift tied to the same providers that dominate AI adoption in banking.
- The business areas with the highest percentages of third-party implementations were human resources (65%), risk and compliance (64%), and operations and IT (56%).
- The share of the top three model providers is significantly higher than the 18% figure in 2022, and the data share rose from 25% in 2022.
- The percentage share of the top three providers for cloud is somewhat lower than it was in the 2022 survey, so cloud concentration was already high two years earlier.
What is cloud concentration risk in financial services?
Cloud concentration risk is the chance that one provider’s failure hits many firms at once. The UK Government warns that disruption at a major supplier could affect multiple firms at the same time, and the ECB says banks’ reliance on a few large providers is potentially leading to idiosyncratic and systemic concentration risks.
Outsourcing Concentration at Eurozone Banks
- The ECB reported that more than 80 significant banks outsource critical payment and administrative services.
- More than half of the banks outsource some of their lending and investment services.
- Most of the ten providers are headquartered outside the EU, mainly in the United States.
- The EBA notes that important services are often outsourced to a few large service providers only.
| Outsourcing measure | Value |
|---|---|
| Significant institutions using critical services from non-EU countries | 73 |
| Outsourced critical and extra-group services offered from non-EU countries | Approximately 22% |
| Outsourcing contracts involving personal data | 70% |
| Significant banks outsourcing critical functions that process personal data | More than 70 |
Source: ECB Banking Supervision newsletter, February 2024
Bank Workload Migration to the Cloud
- The Program on International Financial Systems cites a post-pandemic survey of over 100 global banks for the migration shares below.
- Core workloads are those related to core systems, such as back-end processes and systems that manage customer interactions.
- No public survey of comparable scope has updated these migration shares, so they describe the starting point of the current wave rather than 2026 levels. The bank cloud migration statistics follow individual migration programs since then.
Why it matters: The ECB counts cloud in approximately 15% of all outsourcing contracts, while surveyed North American banks had moved just 12% of workloads. Cloud reached nearly every large bank before it reached the core ledger, so the concentration question now concerns the next wave of migration rather than the last one.
Substitutability and Exit Risk in Critical Outsourcing
- The ECB found that this relatively short list of major providers has remained rather stable in recent years.
- Almost all significant institutions outsource some IT services, and banks also outsource critical functions.
- Cloud contracts that cover critical or important functions make up half of all cloud contracts at ECB-supervised banks.
- Among all contracts covering critical functions, about 50% concern time-critical activities.
| Contracts covering critical functions | Share of contracts |
|---|---|
| Concern time-critical activities | About 50% |
| Cannot be reintegrated in the bank | Around 20% |
| Cannot be substituted through other providers | Around 5% |
Source: ECB Banking Supervision newsletter, February 2024
A contract that can neither come back in-house nor move to a rival has no working exit, only a contingency plan. That residual slice is what supervisors in Frankfurt and London now examine directly.
Cloud Revenue Growth by Provider
- Microsoft reported that Microsoft 365 Commercial cloud revenue increased 16% when adjusted, and 14% on a reported basis.
- Microsoft 365 Consumer cloud revenue increased 24% in the same quarter.
- Microsoft 365 Copilot reached over 30 million paid seats, according to chief executive Satya Nadella.
EU DORA Critical ICT Third-Party Providers
- To build the ESAs’ list of designated CTPPs, the ESAs collected data from the Registers of Information maintained by financial entities, which detail their contractual arrangements for ICT services.
- The designated CTPPs provide ICT services from core infrastructure to business and data services to financial entities of all types and sizes across the European Union.
- The ESAs assessed each provider’s systemic importance, its role in supporting critical or important functions for financial entities, and the substitutability of its services when making designation decisions.
- The list was dated 18 November 2025, and four of its names belong to the Amazon, Google, Microsoft and Oracle groups.
| EU critical ICT third-party provider | Same group designated in UK (July 2026) |
|---|---|
| Accenture plc | No |
| Amazon web Services EMEA Sarl | Yes |
| Bloomberg L.P. | No |
| Capgemini SE | No |
| Colt Technology Services | No |
| Deutsche Telekom AG | No |
| Equinix (EMEA) B.V. | No |
| Fidelity National Information Services, Inc. | No |
| Google Cloud EMEA Limited | Yes |
| International Business Machine Corporation | No |
| InterXion HeadQuarters B.V. | No |
| Kyndryl Inc. | No |
| LSEG Data and Risk Limited | No |
| Microsoft Ireland Operations Limited | Yes |
| NTT DATA Inc. | No |
| Oracle Nederland B.V. | Yes |
| Orange SA | No |
| SAP SE | No |
| Tata Consultancy Services Limited | No |
Source: European Supervisory Authorities CTPP list, November 2025; Bank of England, July 2026
By the numbers: The European Supervisory Authorities named 19 critical ICT third-party service providers, and HM Treasury announced its first designations of four global cloud services and technology providers. The four UK designees all come from groups already on the EU list, so the same hyperscalers now answer to two supervisory regimes.
AWS Quarterly Revenue Trend
- AWS net sales growth, excluding foreign exchange, climbed from 17% to 37% across the six quarters shown.
- Trailing twelve-month AWS net sales reached $148.4 billion in the second quarter of 2026.
- AWS quarterly net sales rose about 44% between the first quarter of 2025 and the second quarter of 2026.
UK Critical Third Parties Regime
- The Bank of England’s announcement set the start of oversight on Monday 13 July 2026.
- Critical Third Parties are technology and other service providers whose services underpin the UK financial system.
- The regime brings four global Cloud Service Providers under direct oversight to help strengthen the resilience of the UK’s financial system.
- Banks, insurers and financial market infrastructures are becoming increasingly reliant on cloud services, according to the UK Government.
| UK Critical Third Party | Designated by | Oversight start |
|---|---|---|
| Amazon Web Services EMEA SARL | HM Treasury | 13 July 2026 |
| Google Cloud EMEA Limited | HM Treasury | 13 July 2026 |
| Microsoft Ireland Operations Ltd | HM Treasury | 13 July 2026 |
| Oracle Corporation UK Limited | HM Treasury | 13 July 2026 |
Source: Bank of England, July 2026
The UK chose a narrower first cut than Brussels. It designated only cloud groups, while the EU list also reaches data centers, telecoms and financial-market data vendors.
Cloud Segment Operating Income
- AWS segment operating income was $16.6 billion, compared with $10.2 billion in the second quarter of 2025.
- Google Cloud operating income rose about 3.1 times year over year.
- AWS converted about 39% of its quarterly segment sales into operating income.
Cloud Outage Risk: The October 2025 AWS Disruption
- AWS said the event started at 11:48 p.m. PDT on October 19 and ended at 2:20 p.m. PDT on October 20 in the N. Virginia (us-east-1) Region.
- There were three distinct periods of impact to customer applications during the disruption.
- Amazon DynamoDB experienced increased API error rates in the N. Virginia (us-east-1) Region in the first phase.
- Across the EU financial sector, the EBA reports that DDoS attacks accounted for 77% of reported incidents in 2025, a separate operational threat from provider outages tracked in trading platform outage records.
| Impact period | Window (PDT) | Affected service |
|---|---|---|
| First | 11:48 PM Oct 19 to 2:40 AM Oct 20 | DynamoDB API error rates |
| Second | 5:30 AM to 2:09 PM Oct 20 | Network Load Balancer connection errors |
| Third | 2:25 AM to 10:36 AM Oct 20 | EC2 instance launch failures |
Source: AWS post-event summary, October 2025
Worth noting: The AWS post-event summary describes three distinct periods of impact to customer applications in one region. It does not name affected customers, so the bank-level cost of that day cannot be measured from the provider’s own account, which is the information gap direct oversight is meant to close.
Public Cloud Spending Trajectory
- The US Treasury, citing Gartner, reported that public cloud services spending was estimated to reach nearly $600 billion in 2023.
- 72% of CIO respondents expect their organization to increase public cloud spending over the next year, while 49% expect to increase private cloud and on-premises spending.
- Worldwide end-user spending on public cloud services was forecast to grow by 20.4% in 2024, driven largely by sectors like banking, per the ECB.
- Spending on analytics runs alongside cloud budgets, as big data spending in finance shows.
Financial Institutions’ 2026 Technology Priorities
- Finastra’s survey records a 40% projected increase in security investment in 2026.
- Only 2% of respondents say they are not using AI at all.
- Institutions recognize that modern platforms and data architecture are essential to scaling AI, strengthening resilience, and delivering customer experience, a pattern also visible in fintech adoption rates.
- Cloud adoption ranks below AI and modernization as a stated priority, which fits a sector where cloud is already in place, and the open work is what runs on it.
Conclusion
Cloud services account for approximately 15% of all outsourcing contracts at ECB-supervised banks, yet the top three providers accounted for 73% of named cloud providers in the UK survey. Adoption is broad, dependence is narrow, and the exit options on critical contracts are thin. That combination explains why the EU and UK now supervise the same hyperscaler groups directly.
The next data points to watch are the first oversight findings from both regimes and whether banks move core workloads at the pace hyperscaler revenue is growing this year. Banks with digital banking front ends on a single provider carry direct exposure to a repeat of an event like the October 2025 disruption.